Erin Yurday
Author
Author
14 October 2026
5 min read
Contents
What is the State Pension?How much is the State Pension?State Pension change over timeState Pension compared to average salaryWhat if the Government didn’t use the triple lock?What happens nextThe guidance on this site is based on our own analysis and is meant to help you identify options and narrow down your choices. We do not advise or tell you which product to buy; undertake your own due diligence before entering into any agreement.
The full new State Pension is £241.30 a week (£12,547.60 a year) in 2026/27.
Since the new State Pension launched in April 2016, the full rate has risen by 55%.
The median full-time salary was £39,039 in April 2025 (ONS).
If the State Pension had risen by the lowest of the three triple lock measures each year, we estimate it would be about £186 a week in 2026/27.
Based on earnings growth, the State Pension is expected to rise by 3.9% in April 2027, to about £250.70 a week, unless September's inflation figure is higher.
The triple lock is under scrutiny once again, and questions remain about whether the Government can afford to keep increasing pensions at the current pace.
Using official data and ClearScore analysis, we look at how the State Pension has changed over time, how it compares to average earnings, and what pensioners would be receiving today if the triple lock had never existed.
The State Pension is a weekly payment paid by the Government to people who reach State Pension age and have built up enough National Insurance contributions or credits.
State Pension age is rising from 66 to 67 between 2026 and 2028.
There are two types of State Pension:
New State Pension – for people reaching pension age on or after April 2016
Basic State Pension – for those who reached pension age before April 2016
This article focuses on the new State Pension, which has been in place since April 2016 and currently pays the highest rates.
In the 2026/27 tax year, the full new State Pension is £241.30 a week (£12,547.60 a year). The full basic State Pension, for people who reached State Pension age before April 2016, is £184.90 a week.
This figure is set using the triple lock, which increases the pension each April by whichever is highest of:
Average earnings growth
Price inflation (CPI)
2.5% minimum guarantee
In April 2024, the State Pension rose by 8.5%, driven by strong wage growth the previous year. That increase added around £900 a year to the income of full new State Pension recipients. It rose by 4.1% in April 2025 (about £470 a year) and by 4.8% in April 2026 (about £575 a year), both based on earnings growth.
Here’s how the full new State Pension has risen since it was introduced in April 2016:
Year | Up-rating percentage | Basis for up-rating | Weekly pension | Annual pension |
Apr-17 | 2.5% | 2.5% Minimum | £159.55 | £8,296.60 |
Apr-18 | 3.0% | Price Inflation (CPI) | £164.35 | £8,545.20 |
Apr-19 | 2.6% | Earnings Growth | £168.60 | £8,767.20 |
Apr-20 | 3.9% | Earnings Growth | £175.20 | £9,110.40 |
Apr-21 | 2.5% | 2.5% Minimum | £179.60 | £9,339.20 |
Apr-22 | 3.1% | Price Inflation (CPI)* | £185.15 | £9,627.80 |
Apr-23 | 10.1% | Price Inflation (CPI) | £203.85 | £10,600.20 |
Apr-24 | 8.5% | Earnings Growth | £221.20 | £11,502.40 |
Apr-25 | 4.1% | Earnings Growth | £230.25 | £11,973.00 |
Apr-26 | 4.8% | Earnings growth | £241.30 | £12,547.60 |
Between April 2016 and April 2026, the full new State Pension rose by 55%. That's more than it would have risen with inflation or earnings growth alone (see below).
Despite strong rises, the State Pension remains modest when compared to typical earnings.
The median full-time salary was £39,039 in April 2025, according to the ONS. The full new State Pension (£12,548 a year) is about a third of that.
This means most retirees rely on additional workplace and private pensions to maintain their standard of living.
However, the triple lock has helped older people avoid real-terms income losses, and over the last decade has risen higher than the average earnings growth.
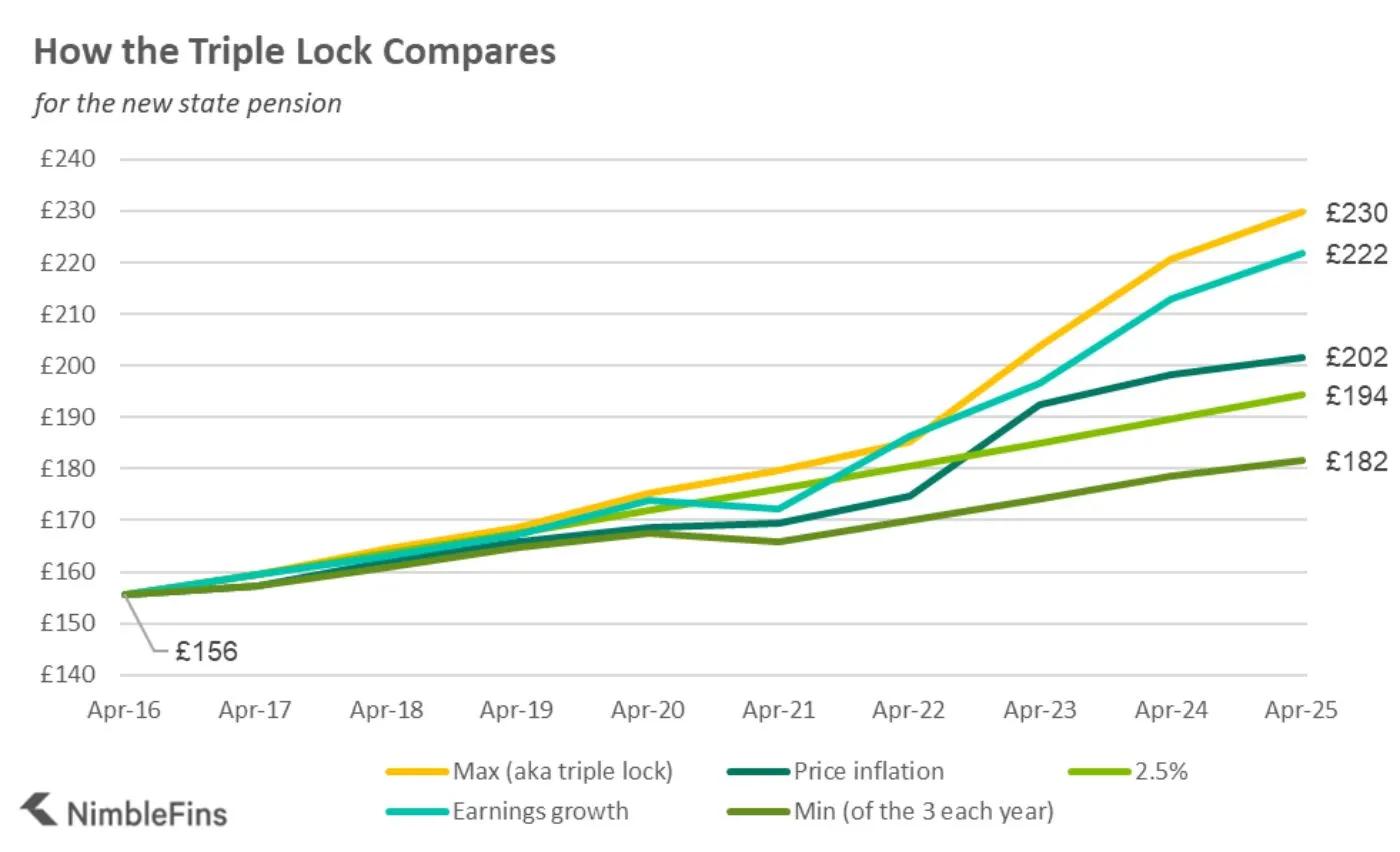
NimbleFins has modelled how the pension would have grown since 2016 if the Government had used only one of the three triple-lock components each year:
A flat 2.5% rise
Inflation (CPI) each year
Earnings growth each year
And if the Government used the lowest of the three figures, rather than the highest.
Year | Max rise (triple lock) | Price inflation | 2.5% rise | Earnings growth | Minimum of the 3 |
Apr 2016 | £155.65 | £155.65 | £155.65 | £155.65 | £155.65 |
Apr 2017 | £159.55 | £157.21 | £159.55 | £159.39 | £156.82 |
Apr 2018 | £164.35 | £161.92 | £163.53 | £163.05 | £160.82 |
Apr 2019 | £168.60 | £168.51 | £167.62 | £167.29 | £165.48 |
Apr 2020 | £175.20 | £168.05 | £171.81 | £173.82 | £170.63 |
Apr 2021 | £179.60 | £178.47 | £176.10 | £172.08 | £168.81 |
Apr 2022 | £185.15 | £174.72 | £180.51 | £186.38 | £174.20 |
Apr 2023 | £203.85 | £192.37 | £185.02 | £196.01 | £174.32 |
Apr 2024 | £221.20 | £198.33 | £189.84 | £212.93 | £180.58 |
Apr 2025 | £230.25 | £201.71 | £194.39 | £222.93 | £181.59 |
Apr 2026 | £241.30 | £216.68 | £199.25 | £232.50 | £185.95 |
Under the triple lock, the State Pension has risen 48% from £155.65 in April 2016 to £230.25 in April 2025.
If the Treasury used earnings-only rises, it would be about £232.50, about £9 a week less.
Under inflation-only rises, it would be about £216.70, about £25 a week less.
Under a flat 2.5% rise each year, it would be about £199.25, about £42 a week less.
If the Government used the lowest of the three measures each year, the State Pension would be about £186 a week, about £55 a week or £2,880 a year less.
Over nine years, the triple lock has delivered thousands of pounds more for pensioners than any alternative method.
Despite the bumper rise, this chart shows the state pension compared to average spending for the 65-74 age bracket, for the five different income quintiles and the overall average.
The triple lock is expensive, and economists have long questioned whether it is sustainable. The Government has committed to keeping it for this Parliament. The April 2027 increase will be based on whichever is highest: earnings growth for May to July 2026 (3.9%), CPI inflation for September 2026 (published on 21 October 2026), or 2.5%. If earnings growth is the highest, the full new State Pension would rise to about £250.70 a week (£13,036 a year).
The income tax personal allowance is frozen at £12,570 until April 2031, so the full new State Pension is expected to be higher than the personal allowance from April 2027.
Read more:
Author
14 October 2026
5 min read
Contents
What is the State Pension?How much is the State Pension?State Pension change over timeState Pension compared to average salaryWhat if the Government didn’t use the triple lock?What happens nextThe guidance on this site is based on our own analysis and is meant to help you identify options and narrow down your choices. We do not advise or tell you which product to buy; undertake your own due diligence before entering into any agreement.
Author
Erin was the founder of NimbleFins, a data driven personal finance site. A former derivatives trader and finance expert at the Stanford Graduate School, Erin turns research into plain answers so you can understand your credit.
Author
14 October 2026
5 min read
Contents
What is the State Pension?How much is the State Pension?State Pension change over timeState Pension compared to average salaryWhat if the Government didn’t use the triple lock?What happens nextThe guidance on this site is based on our own analysis and is meant to help you identify options and narrow down your choices. We do not advise or tell you which product to buy; undertake your own due diligence before entering into any agreement.
The full new State Pension is £241.30 a week (£12,547.60 a year) in 2026/27.
Since the new State Pension launched in April 2016, the full rate has risen by 55%.
The median full-time salary was £39,039 in April 2025 (ONS).
If the State Pension had risen by the lowest of the three triple lock measures each year, we estimate it would be about £186 a week in 2026/27.
Based on earnings growth, the State Pension is expected to rise by 3.9% in April 2027, to about £250.70 a week, unless September's inflation figure is higher.
The triple lock is under scrutiny once again, and questions remain about whether the Government can afford to keep increasing pensions at the current pace.
Using official data and ClearScore analysis, we look at how the State Pension has changed over time, how it compares to average earnings, and what pensioners would be receiving today if the triple lock had never existed.
The State Pension is a weekly payment paid by the Government to people who reach State Pension age and have built up enough National Insurance contributions or credits.
State Pension age is rising from 66 to 67 between 2026 and 2028.
There are two types of State Pension:
New State Pension – for people reaching pension age on or after April 2016
Basic State Pension – for those who reached pension age before April 2016
This article focuses on the new State Pension, which has been in place since April 2016 and currently pays the highest rates.
In the 2026/27 tax year, the full new State Pension is £241.30 a week (£12,547.60 a year). The full basic State Pension, for people who reached State Pension age before April 2016, is £184.90 a week.
This figure is set using the triple lock, which increases the pension each April by whichever is highest of:
Average earnings growth
Price inflation (CPI)
2.5% minimum guarantee
In April 2024, the State Pension rose by 8.5%, driven by strong wage growth the previous year. That increase added around £900 a year to the income of full new State Pension recipients. It rose by 4.1% in April 2025 (about £470 a year) and by 4.8% in April 2026 (about £575 a year), both based on earnings growth.
Here’s how the full new State Pension has risen since it was introduced in April 2016:
Year | Up-rating percentage | Basis for up-rating | Weekly pension | Annual pension |
Apr-17 | 2.5% | 2.5% Minimum | £159.55 | £8,296.60 |
Apr-18 | 3.0% | Price Inflation (CPI) | £164.35 | £8,545.20 |
Apr-19 | 2.6% | Earnings Growth | £168.60 | £8,767.20 |
Apr-20 | 3.9% | Earnings Growth | £175.20 | £9,110.40 |
Apr-21 | 2.5% | 2.5% Minimum | £179.60 | £9,339.20 |
Apr-22 | 3.1% | Price Inflation (CPI)* | £185.15 | £9,627.80 |
Apr-23 | 10.1% | Price Inflation (CPI) | £203.85 | £10,600.20 |
Apr-24 | 8.5% | Earnings Growth | £221.20 | £11,502.40 |
Apr-25 | 4.1% | Earnings Growth | £230.25 | £11,973.00 |
Apr-26 | 4.8% | Earnings growth | £241.30 | £12,547.60 |
Between April 2016 and April 2026, the full new State Pension rose by 55%. That's more than it would have risen with inflation or earnings growth alone (see below).
Despite strong rises, the State Pension remains modest when compared to typical earnings.
The median full-time salary was £39,039 in April 2025, according to the ONS. The full new State Pension (£12,548 a year) is about a third of that.
This means most retirees rely on additional workplace and private pensions to maintain their standard of living.
However, the triple lock has helped older people avoid real-terms income losses, and over the last decade has risen higher than the average earnings growth.
NimbleFins has modelled how the pension would have grown since 2016 if the Government had used only one of the three triple-lock components each year:
A flat 2.5% rise
Inflation (CPI) each year
Earnings growth each year
And if the Government used the lowest of the three figures, rather than the highest.
Year | Max rise (triple lock) | Price inflation | 2.5% rise | Earnings growth | Minimum of the 3 |
Apr 2016 | £155.65 | £155.65 | £155.65 | £155.65 | £155.65 |
Apr 2017 | £159.55 | £157.21 | £159.55 | £159.39 | £156.82 |
Apr 2018 | £164.35 | £161.92 | £163.53 | £163.05 | £160.82 |
Apr 2019 | £168.60 | £168.51 | £167.62 | £167.29 | £165.48 |
Apr 2020 | £175.20 | £168.05 | £171.81 | £173.82 | £170.63 |
Apr 2021 | £179.60 | £178.47 | £176.10 | £172.08 | £168.81 |
Apr 2022 | £185.15 | £174.72 | £180.51 | £186.38 | £174.20 |
Apr 2023 | £203.85 | £192.37 | £185.02 | £196.01 | £174.32 |
Apr 2024 | £221.20 | £198.33 | £189.84 | £212.93 | £180.58 |
Apr 2025 | £230.25 | £201.71 | £194.39 | £222.93 | £181.59 |
Apr 2026 | £241.30 | £216.68 | £199.25 | £232.50 | £185.95 |
Under the triple lock, the State Pension has risen 48% from £155.65 in April 2016 to £230.25 in April 2025.
If the Treasury used earnings-only rises, it would be about £232.50, about £9 a week less.
Under inflation-only rises, it would be about £216.70, about £25 a week less.
Under a flat 2.5% rise each year, it would be about £199.25, about £42 a week less.
If the Government used the lowest of the three measures each year, the State Pension would be about £186 a week, about £55 a week or £2,880 a year less.
Over nine years, the triple lock has delivered thousands of pounds more for pensioners than any alternative method.
Despite the bumper rise, this chart shows the state pension compared to average spending for the 65-74 age bracket, for the five different income quintiles and the overall average.
The triple lock is expensive, and economists have long questioned whether it is sustainable. The Government has committed to keeping it for this Parliament. The April 2027 increase will be based on whichever is highest: earnings growth for May to July 2026 (3.9%), CPI inflation for September 2026 (published on 21 October 2026), or 2.5%. If earnings growth is the highest, the full new State Pension would rise to about £250.70 a week (£13,036 a year).
The income tax personal allowance is frozen at £12,570 until April 2031, so the full new State Pension is expected to be higher than the personal allowance from April 2027.
Read more:
Author
14 October 2026
5 min read
Contents
What is the State Pension?How much is the State Pension?State Pension change over timeState Pension compared to average salaryWhat if the Government didn’t use the triple lock?What happens nextThe guidance on this site is based on our own analysis and is meant to help you identify options and narrow down your choices. We do not advise or tell you which product to buy; undertake your own due diligence before entering into any agreement.
Author
Erin was the founder of NimbleFins, a data driven personal finance site. A former derivatives trader and finance expert at the Stanford Graduate School, Erin turns research into plain answers so you can understand your credit.